The 2026 Nobel in Economics' Great Paradox — Why the Model That Saved Economies Missed the Crisis
Summary
The 2026 Nobel Prize in Economic Sciences has been awarded jointly to Robert E. Hall (Stanford University) and Michael Woodford (Columbia University) for establishing the microeconomic foundations of macroeconomic stabilization — a contribution that fundamentally transformed how central banks analyze and conduct monetary policy. Following the catastrophic failure of Keynesian macromodels during the 1970s stagflation, Hall and Woodford rebuilt the discipline on the premise that households and businesses are forward-looking decision-makers whose expectations about the future shape present economic outcomes, creating the intellectual architecture now known as the New Keynesian framework. That framework now sits at the core of the policy models used by the Federal Reserve, the European Central Bank, and the Bank of England, and it provided the academic foundation for forward guidance as a monetary policy instrument during the zero-lower-bound era after 2008. Yet the same elegantly constructed models failed to anticipate the 2008 global financial crisis, and a well-documented "forward guidance puzzle" reveals that standard DSGE models systematically overestimate the real-world effectiveness of the very policy tool Woodford helped design — a paradox that Woodford himself is actively working to resolve. This Nobel Prize is both an overdue recognition of economics' greatest modern achievement and the most candid possible illustration of the discipline's deepest unresolved tension: whether the next generation of heterogeneous agent models and cognitive expectation frameworks can finally close the gap between elegant theory and messy reality is the defining question for macroeconomics in the years ahead.
> **Category**: economy
Key Points
The Collapse of Keynesian Models and the Reconstruction on Microeconomic Foundations
The 1970s oil shocks exposed the fundamental limits of Keynesian macroeconomic models in the most brutal possible way. The standard prescription — government spends, economy recovers — met stagflation head on and failed completely, with unemployment and inflation rising simultaneously while Western economies endured a lost decade of low growth and policy paralysis. Nobel Committee member Timo Boppart captured the failure economically: "This is the Keynesian recipe and it worked well — until it didn't." What Hall and Woodford did next was radical in its simplicity: instead of tinkering with the existing framework, they rebuilt it on a completely different foundation — the premise that households and businesses make decisions by looking forward, anticipating future conditions, and adjusting behavior accordingly. The Nobel Committee described the core insight as follows: "Economic outcomes are the result of millions of decisions made at the microlevel by households and businesses." This reorientation from statistical correlations between macro variables to the micro-level decision logic of actual economic agents is the methodological revolution that earned this prize — and the framework it produced, now called the New Keynesian model, sits at the analytical core of the Fed's FRB/US, the ECB's NAWM, and the Bank of England's COMPASS. Without this reconstruction, central banks navigating 21st-century economies would still be relying on tools calibrated for a world that no longer exists.
Hall's Random Walk Consumption — A Eureka Moment and Its Four-Decade Legacy
Robert Hall's landmark 1978 paper in the Journal of Political Economy demonstrated empirically that consumption changes by rationally forward-looking households are fundamentally unpredictable — a result the Nobel Committee described as "something of a eureka moment." Former IMF chief economist Olivier Blanchard offered a characteristically direct reaction: this finding "is not good news for forecasters, or policymakers." That cold assessment, counterintuitively, is precisely what makes the research transformative: it began from an honest reckoning with how hard economic prediction actually is, rather than offering false comfort. Hall and Mishkin's 1982 follow-up, using panel data from roughly two thousand households, refined the picture significantly — finding that about 80 percent of families base consumption on forward-looking expectations, while the remaining 20 percent spend income as it arrives, without any forward-looking adjustment. This hand-to-mouth 20 percent turns out to be extraordinarily important four decades later, because it became the empirical motivation for the Heterogeneous Agent New Keynesian (HANK) model — a frontier research program that explicitly models income inequality and distributional policy effects. Hall's 2005 AER paper extended this micro-grounded approach to labor markets, improving the framework's ability to explain unemployment dynamics. The arc from the 1978 consumption paper to today's HANK research is a direct intellectual lineage — and the fact that it took four decades for the field to formally incorporate what Hall found in 1982 says something important about both the slowness of scientific progress and the depth of the original insight.
Woodford's Monetary Policy Revolution — From Interest and Prices to Forward Guidance
Michael Woodford's 2003 book Interest and Prices (Princeton University Press, 785 pages) provided the theoretical foundation for maintaining price stability through interest rate policy alone — without any external nominal anchor in gold or money supply targets. Princeton's Lars Svensson described it as "immensely influential," and the verdict has only strengthened with time. Woodford extended this theoretical architecture in his 2012 Jackson Hole symposium paper, which provided the scholarly case for "explicit statements by a central bank about the outlook for future policy" — forward guidance — as an effective instrument when conventional rate policy hits the zero lower bound, and the Federal Reserve's subsequent adoption of this strategy drew directly on that work. In 2024, Woodford received Northwestern University's Nemmers Prize ($300,000) — recognition that preceded the Nobel and reflected his already towering influence on the field. In his 2014 Minneapolis Fed interview, Woodford offered a characteristically honest assessment of the New Keynesian framework: it was adopted "not because they are perfect models, but because what we had before was even less suitable for that purpose." That level of candor about one's own theoretical contributions is rare in any academic discipline, and it reflects a genuine understanding that the work remains incomplete. Woodford's current research focus on alternative models of expectation formation represents the next phase of building on — and correcting — the framework he helped create.
The Forward Guidance Puzzle — The Paradox the Model Revealed About Itself
A 2023 paper in JPE Macroeconomics by Del Negro, Giannoni, and Patterson at the Federal Reserve Bank of New York identified what they termed the "forward guidance puzzle": standard DSGE models "grossly overestimate" the macroeconomic impact of forward guidance in practice. This is a genuine paradox — the policy tool that Woodford's theoretical work helped legitimize turns out to be substantially overstated in effect by the very models that justified it. Woodford himself has addressed this directly rather than deflecting it: his 2019 AER paper with Garcia-Schmidt critiques the unrealism of perfect-foresight assumptions embedded in the standard framework and proposes finite-horizon reasoning as a more realistic model of how agents actually think about the future. The paper's conclusion — that commitments to hold rates low are expansionary, but less dramatically so than perfect-foresight analysis predicts — does not fully resolve the puzzle, but it represents the most credible existing attempt to do so from within the New Keynesian tradition. Woodford's own measured assessment in his AP interview — that forward guidance "didn't magically solve the problem, but I think it was an important contribution" — reads as an honest acknowledgment of this tension. That a Nobel laureate is the person most actively working to fix the problems in his own foundational work is, in its own way, the most reassuring thing about this research program.
How Central Banks Actually Use These Models — Common Language, Not Definitive Truth
The Banque de France's October 2026 working paper offers a clarifying perspective on how the New Keynesian framework actually functions in central bank practice: DSGE models "remain valuable less as definitive descriptions of the economy" and more as "a common language for organizing economic arguments." This is a significantly more modest claim than "the model tells us what to do," and it's the accurate one. The Fed does not run FRB/US and read off the correct interest rate; it uses a portfolio of models — FRB/US, EDO, and SIGMA among them — as complementary lenses that illuminate different aspects of a complex situation. The ECB runs NAWM; the Bank of England runs COMPASS. All of them use additional judgmental overlays, scenario analyses, and expert assessments alongside the formal models. Blanchard's formulation is precise and worth remembering: "We need different types of macroeconomic models for different purposes." The value of the Hall-Woodford lineage is not that it provides definitive answers — it is that it structures the questions more rigorously and makes the assumptions underlying any given policy conclusion explicit and debatable. Understanding this distinction — model as structured thinking tool versus model as oracle — is the most important single thing a non-specialist reader can take away from this Nobel. The equations are not the policy; the judgment about what the equations mean for a particular situation, made by a fallible human being in a press conference, is the policy.
Positive & Negative Analysis
Positive Aspects
- A Revolutionary Upgrade in Central Bank Policy Instruments
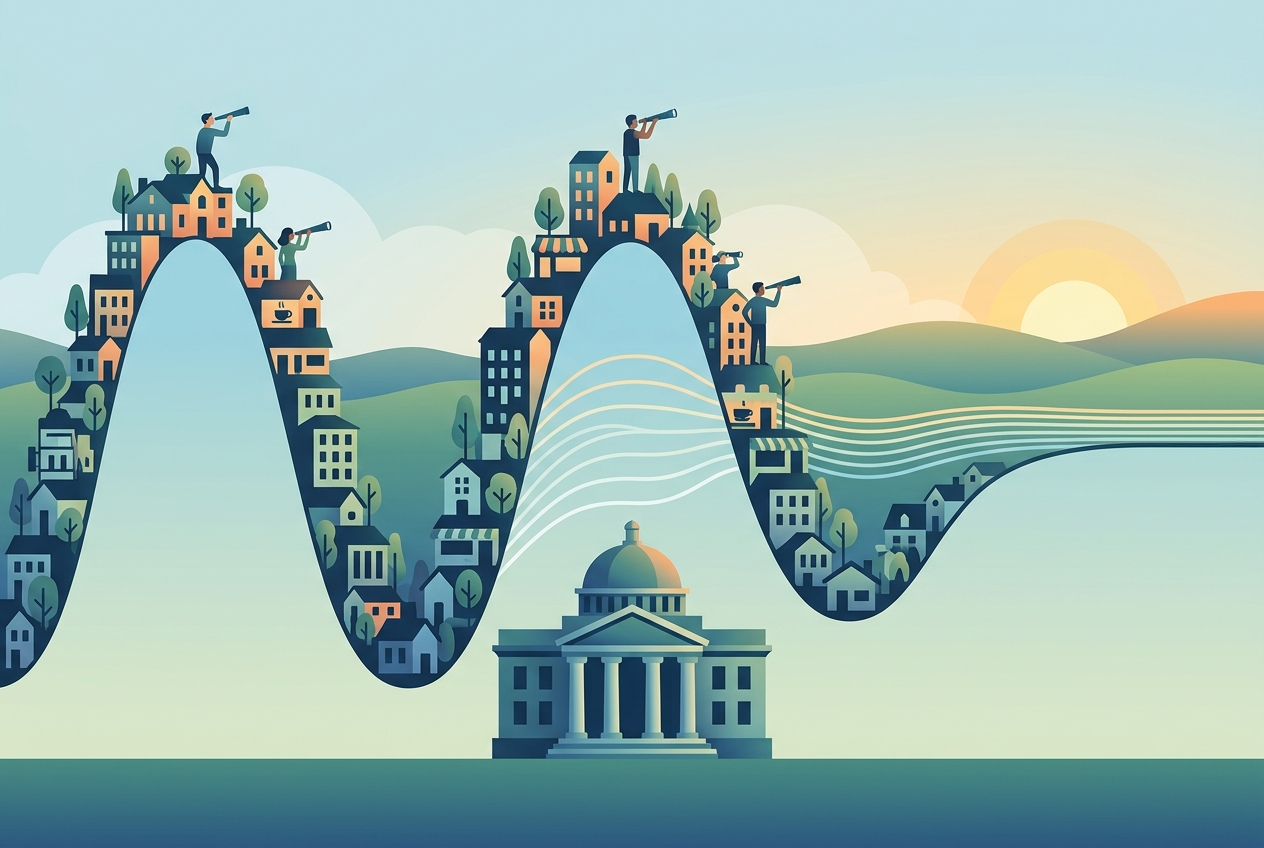
Hall and Woodford's research fundamentally expanded the toolkit available to central banks beyond the single lever of adjusting money supply. Where 1970s Keynesian models offered essentially one prescription — fiscal expansion drives recovery — the New Keynesian framework built on their work requires central banks to think systematically about how households and firms respond to policy signals, not just to policy actions themselves. When the Federal Reserve raised rates to 3.75–4.00% at its September 2026 FOMC meeting and communicated explicitly that "inflation remains elevated" and that the action would "support a timelier return to the Committee's 2 percent goal," the communication itself was functioning as a distinct policy instrument — precisely the insight Woodford institutionalized in the academic literature. Central banks today do not simply move interest rates; they explain why they are moving, signal where policy is headed, and actively shape market expectations as a deliberate and separable tool. The Nobel Committee recognized this directly: "The laureates have helped us smooth out the economy's peaks and troughs." This is not an abstract academic contribution; it is a measurable improvement in the governance capacity of institutions that shape the financial conditions facing billions of people, and the distance between 1970s-era crisis response and today's more calibrated approach reflects in part the theoretical work this prize recognizes.
- Breaking Down the Wall Between Microeconomics and Macroeconomics
The methodological contribution of this research is frequently underappreciated, but it may be the most durable part of the legacy. Hall started from consumer behavior — traditionally a microeconomic domain — and used it to reconstruct how the macroeconomy works from the ground up. Woodford began from pure theory and arrived at actual central bank practice. MIT's Iván Werning described this as recognizing "research that pushes our understanding of macroeconomics from the bottom up" — and that description captures the methodological revolution precisely. Before this work, macroeconomics and microeconomics operated largely as separate enterprises with their own modeling traditions, their own journals, and their own assumptions that often contradicted each other. Hall and Woodford's research made it impossible to do credible macroeconomics without grounding the aggregate behavior in micro-level decision logic. This approach has since spread beyond economics into labor research, environmental policy design, public health modeling, and urban planning — any domain where researchers need to connect individual-level decisions to aggregate social outcomes now draws on conceptual tools that the New Keynesian program helped develop. The dissolution of an artificial disciplinary boundary is a contribution that compounds across decades.
- Expanded Crisis Response Capacity and the Zero Lower Bound Problem
The practical value of forward guidance as a policy instrument — which Woodford's 2012 Jackson Hole paper helped justify — is most clearly visible in the specific problem it was designed to solve: what a central bank does when conventional interest rate cuts are exhausted because rates have hit zero. Before this theoretical work, central banks at the zero lower bound essentially had one remaining option: unconventional balance sheet expansion. Woodford's framework provided the analytical basis for a second option — committing credibly to a future policy path, thereby shaping current expectations and influencing present economic behavior even when the policy rate itself cannot move further. Woodford's own assessment was measured: forward guidance "didn't magically solve the problem, but I think it was an important contribution." That restraint is accurate — the tool is not a cure, but it demonstrably extends the central bank's effective policy space at the moments when that extension matters most. The Committee's observation that this research helps central banks better manage disruptions like "energy crises or sudden changes in how much households consume" reflects a real improvement in institutional responsiveness, even if the improvement falls well short of perfect foresight.
- A Self-Correcting Research Program That Confronts Its Own Failures
Perhaps the most encouraging feature of this research tradition is that its leading practitioner is actively working to fix its most important known weaknesses rather than defending the existing framework against criticism. Woodford's current research agenda focuses explicitly on "alternative models of expectation formation" — bounded rationality approaches that replace the perfect-rationality assumption with more realistic models of how people actually form beliefs. The Garcia-Schmidt and Woodford 2019 AER paper directly tackles the forward guidance puzzle by proposing finite-horizon reasoning as a correction to perfect-foresight analysis. The HANK model development at the research frontier builds on Hall's own 1982 finding about hand-to-mouth consumers, incorporating income heterogeneity and distributional effects that the original representative-agent models structurally excluded. Blanchard's prescription — "improved rather than discarded" — is actually being followed in the research literature. A scientific tradition that can absorb serious empirical challenges, identify its structural weaknesses, and redirect research effort toward addressing them is more valuable than one that claims to have already found the answer. The fact that this tradition continues to evolve is not a sign of weakness; it is the best possible evidence that the foundational framework is worth improving.
Concerns
- The Rational Expectations Assumption and Its Fundamental Realism Problem
The most foundational critique of Hall and Woodford's framework targets the premise that holds the whole structure together: the assumption that households and firms form rational expectations about the future and act on them consistently. Behavioral economics has spent decades documenting, across field after field, that humans are systematically irrational in highly predictable ways — prone to loss aversion, present bias, herding, and a host of other cognitive patterns that rational-expectations models cannot accommodate. Hall and Mishkin's own 1982 data already showed that roughly 20 percent of households exhibit hand-to-mouth consumption behavior with no discernible forward-looking adjustment — and in practice, particularly among lower-income populations facing genuine liquidity constraints, that proportion is likely substantially higher. A model built entirely on rational agents has a structural blind spot for any crisis generated by irrational speculation, panic, herd behavior, or the kind of leveraged asset-price dynamics that preceded 2008. Paul Romer's 2016 charge that "for more than three decades, macroeconomics has gone backwards" overstates the overall indictment, but it points squarely at this weakness in the rational-expectations edifice. The deeper operational problem is whether policymakers consistently remember that this framework illuminates a particular slice of economic reality rather than the whole of it — and the model's mathematical elegance makes that critical distinction easy to lose sight of under deadline pressure.
- The Absence of Finance and the Painful Lesson of 2008
The 2008 global financial crisis remains the most damaging exhibit against the New Keynesian framework, and the damage is structural rather than incidental. The representative-household assumption that sits at the core of standard DSGE models structurally excludes the phenomena that made 2008 catastrophic: the gradual accumulation of leverage inside financial intermediaries, the interconnected web of risk exposures across institutions, and the fundamentally non-rational spiral of panic and forced selling that amplified a housing correction into a global systemic crisis. Post-crisis model updates — the ECB's NAWM II, the Bank of England's revised COMPASS — added financial friction blocks, but as Blanchard observed, that amounts to adding a room to an existing building rather than redesigning the architecture. His 2018 Oxford Review of Economic Policy diagnosis — that "the goal of full integration has proven counterproductive" — points at something deeper: the ambition to build one model that handles everything is itself the design error. "No model can be all things to all people." The question that matters going forward is whether policymakers have genuinely internalized this lesson, or whether the pattern of being structurally blindsided by what the prevailing model cannot see will repeat when the next systemic stress arrives.
- The Structural Fragility of Communication-Dependent Policy
Forward guidance as a policy tool rests on a single prerequisite that is neither guaranteed nor easy to restore once lost: market trust in central bank communications. When that trust holds, forward guidance can meaningfully extend the central bank's policy reach. When it breaks down, the same tool that was meant to stabilize expectations can instead amplify uncertainty. The Fed's repeated "transitory" inflation communications in 2021–2022 — which proved badly wrong — demonstrated in real time that forward guidance is a double-edged instrument: when communication becomes the policy, a miscommunication becomes a policy failure. The forward guidance puzzle adds another layer to this fragility: the standard DSGE models that justify the tool systematically overstate its real-world effectiveness, meaning that policymakers relying on those models may be even more confident in the instrument's potency than the evidence warrants. As PCE inflation sits at 3.8% and every word from a Fed press conference gets forensically parsed by markets, the real-world cost of this communication fragility is not theoretical — it is embedded in market volatility and household uncertainty in ways that have direct distributional consequences. The model's reliance on the central bank's communicative competence as a load-bearing structural assumption is, I think, its most underappreciated vulnerability.
- The Risk That Nobel Authority Suppresses Needed Criticism
The most subtle concern is also the most structurally important: the Nobel Prize's authority could discourage exactly the kind of rigorous scrutiny the New Keynesian framework most needs at precisely the moment when it matters. Economics has a consistent historical pattern of intellectual overconfidence preceding its most costly failures. The self-congratulatory tone of the Great Moderation era — when some economists publicly celebrated having solved the business cycle problem — was the intellectual overture to 2008. If this award functions as an academic imprimatur that discourages hard questions about the framework's documented limitations — the forward guidance puzzle, the absence of finance, the rational expectations assumption — that outcome would be worse than the absence of a prize. Research funding dynamics compound this risk: awards of this stature tend to direct resources toward the recognized framework and away from alternative approaches, potentially starving the heterodox work that might identify the next structural blind spot. Woodford himself has pushed back against any such complacency — his comment that periodic policy framework reexamination is "very appropriate" is a public signal that he does not regard the work as finished. Whether the broader academic and policy community shares that specific intellectual humility, or whether the Nobel functions as a permission slip to stop asking hard questions, is a structural risk this prize cannot resolve on its own terms.
Outlook
The most immediately observable effect of this Nobel Prize — over the next one to six months — will be a sharp surge of attention toward New Keynesian macroeconomics in universities and policy institutions worldwide. Economics departments will see pronounced upticks in enrollment in DSGE-related courses and in graduate school interest. On a more practical level, the award functions as an academic endorsement of the policy frameworks central banks are currently deploying in a high-inflation environment. The Fed raised rates to 3.75–4.00% at its September 2026 FOMC meeting, with PCE inflation at 3.8%, core PCE at 3.4%, and unemployment at 4.1%. Fed staff project a return to the 2% target no earlier than 2029. In this context, awarding the Nobel to the economists who built the theoretical case for forward guidance and expectation-anchored policy management works as an implicit academic seal of approval for what central banks are currently doing — and in practical terms, central bank governors can be expected to invoke model-based analysis more explicitly in press conferences as a result, reinforcing the legitimacy of communication-centered policy as a governance tool. The Fed's FRB/US model has been in operational use since 1996, but a Nobel Prize substantially raises its public profile and the frequency with which journalists and market participants engage with it seriously.
That said, this endorsement effect could cut both ways, and it is worth naming the risk explicitly. The Nobel Prize's authority could suppress exactly the kind of constructive scrutiny the existing framework most needs, at precisely the moment when it matters. The most dangerous junctures in economic history have consistently arrived right after someone declared the central problem solved. The self-congratulation of the Great Moderation era — when some economists publicly celebrated having tamed the business cycle — was the direct overture to the 2008 catastrophe. I genuinely hope the next six months generate serious academic debate about this award, including honest examination of the forward guidance puzzle and the model's known structural limitations, rather than allowing those questions to be buried under the prestige of the prize. Woodford himself signaled in his AP interview that periodic reexamination of the policy framework is "very appropriate." His own words tell us the framework is not finished. The short-run question is whether the broader policy community internalizes that humility or treats the Nobel as a closing argument.
Looking out over a medium-term horizon of six months to two years, the most consequential impact will likely be the acceleration of next-generation DSGE model development. Woodford's own current research agenda — centered on bounded rationality and heterogeneous agents — stands to receive significant additional funding and scholarly attention as a direct result of this prize. The Heterogeneous Agent New Keynesian (HANK) model is already actively developing at the frontier of the research literature; the Nobel recognition should dramatically increase the resources and talent flowing toward that program. HANK models build explicitly on Hall's 1982 finding about hand-to-mouth consumers, incorporating income distribution and the distributional effects of fiscal policy as endogenous model features rather than afterthoughts. In a real sense, HANK is the field finally catching up with what Hall documented four decades ago — which says something both about how slowly science sometimes moves and about the fact that it is at least moving in the right direction.
Also worth tracking in the medium term is the spread of a model-portfolio approach among central banks globally. The Banque de France's October 2026 paper makes the explicit institutional case that "central banks therefore benefit from using a portfolio of models" rather than placing excessive confidence in any single framework. The Fed already runs FRB/US, EDO, and SIGMA in parallel. The Bank of England is rebuilding its COMPASS model following Bernanke's 2024 review recommendations. The ECB has added a financial sector to NAWM II. Paradoxically, this Nobel Prize may reinforce not dependence on a single canonical model but rather the discipline of using multiple complementary tools — each illuminating a different facet of economic reality. Blanchard's view that "we need different types of macroeconomic models for different purposes" looks set to become the profession's practical operating consensus over this horizon. The more this model-portfolio approach becomes institutionalized, the more individual model biases offset each other in the aggregate, and the more robust and defensible policy judgments become.
Looking further out — a two-to-five year horizon — the most interesting open question is what the successor to New Keynesian models will look like in practice. Two tracks appear to be running in parallel. One is the cognitive expectation formation track that Woodford is actively pursuing: replacing the perfect-rationality assumption with models that more faithfully represent how people actually form beliefs about the future. The Garcia-Schmidt and Woodford 2019 AER paper establishes the starting point, and the finding there — that holding rates low is expansionary but less powerfully so than perfect-foresight analysis predicts — suggests this line of research could meaningfully reduce the forward guidance puzzle without abandoning the broader framework. The other track is the rise of machine learning and big-data methods in macroeconomic forecasting. Traditional DSGE models hold a comparative advantage in structural interpretability and theoretical coherence; machine learning approaches often have the edge in short-horizon prediction accuracy. How these two methodologies interact, compete, and possibly converge over the next several years will determine the shape of the field's next chapter. A hybrid approach that combines structural interpretability with machine learning's predictive accuracy would be the genuine intellectual heir to what Hall and Woodford built.
Beyond five years, the deepest challenges are structural ones that the existing framework was not designed to address. Climate transition costs, aging-population shifts in savings and consumption behavior, and AI-driven labor market disruption represent exactly the kind of structural breaks that standard New Keynesian models have no built-in mechanism to handle. If Hall and Woodford's framework was the theoretical response to the structural rupture of the 1970s, then the decade ahead may require an equivalent theoretical leap for this generation of disruptions. Whether that leap happens from within the current paradigm or emerges from outside it remains a genuinely open question — and the honest answer is that no one can say. What is not open is the pattern itself: in economics, crises produce new theories, and new theories get tested in the next crisis. This Nobel Prize closes one chapter of that cycle and opens the next.
To sketch three scenarios: in the optimistic case, the research investment catalyzed by this award accelerates HANK and cognitive-expectation modeling to the point where a third-generation New Keynesian model — one that genuinely incorporates financial frictions, income heterogeneity, and bounded rationality — enters central bank practice within five years, meaningfully improving the policy response capacity available for the next crisis. In the baseline case, current models improve incrementally while machine learning tools are deployed alongside them, with no fundamental paradigm shift but with a slow and steady reduction in the framework's known blind spots. In the pessimistic case, the Nobel's authority breeds overconfidence in the existing framework, and the next financial crisis once again produces the familiar lament that the models did not see it coming — followed by another two-decade cycle of emergency reconstruction. History consistently shows that the most dangerous scenario is not a flawed model — it is uncritical belief in a good one. This award's highest possible outcome would be if its recognition of past achievement simultaneously renewed the profession's commitment to confronting the work that remains undone.
Sources / References
- The Prize in Economic Sciences 2026 — Press Release — The Royal Swedish Academy of Sciences — The Prize in Economic Sciences 2026 — Press Release
- Americans Hall, Woodford win 2026 Nobel economics prize — AP via phys.org — Americans Hall, Woodford win 2026 Nobel economics prize
- Nobel Economics 2026: Robert Hall and Michael Woodford win for macroeconomic stabilization — Fortune — Nobel Economics 2026: Robert Hall and Michael Woodford win for macroeconomic stabilization
- Americans Hall, Woodford win 2026 Nobel economics prize — NBC News — Americans Hall, Woodford win 2026 Nobel economics prize
- Interview with Michael Woodford — Federal Reserve Bank of Minneapolis — Interview with Michael Woodford
- The Forward Guidance Puzzle (Staff Report No. 574) — Federal Reserve Bank of New York — The Forward Guidance Puzzle (Staff Report No. 574)
- On the future of macroeconomic models — Oxford Review of Economic Policy (Blanchard 2018) — On the future of macroeconomic models
- DSGE Models in Central Banks: Progress and Prospects (WP 1066) — Banque de France — DSGE Models in Central Banks: Progress and Prospects (WP 1066)
- FOMC Statement September 16, 2026 — Board of Governors of the Federal Reserve System — FOMC Statement September 16, 2026