Adobo Never Became the Next Pad Thai — and It Had Nothing to Do With Taste
Summary
Filipino cuisine has achieved an unprecedented wave of international recognition in 2025–2026, including the inaugural Michelin Guide Philippines launch on October 30, 2025, TasteAtlas ranking chicken inasal third in the world among chicken dishes (rating 4.4), and the Philippines' selection as host of the 10th UN Tourism World Forum on Gastronomy Tourism — yet this remarkable critical acclaim has not translated into proportional global restaurant presence or market penetration. Despite a global Filipino restaurant market estimated at approximately $3.8 billion, over 54 percent of that revenue originates within the Asia-Pacific region, leaving the country's international footprint a fraction of Thai or Japanese cuisine's reach. The structural barriers are well-documented: 500-plus years of colonial history under Spain, the United States, and Japan produced a deeply hybridized culinary identity that resists the kind of single-icon branding that propelled pad thai and sushi to global dominance, while Thailand's government-backed Global Thai program invested 500 million baht (roughly US$15 million) at launch and expanded overseas Thai restaurant numbers from approximately 5,500 in 2002 to 17,478 by January 2024, and South Korea's K-Food exports reached a record $13.03 billion in 2024 — benchmarks that highlight the scale of strategic investment the Philippines has yet to commit. The Philippines' most underdeployed asset may be its 10.8-million-strong overseas diaspora, spread across the Americas, Asia-Pacific, and the Middle East, whose informal culinary ambassadorship could be transformed into systematic restaurant expansion given coordinated national support. Until real budget follows the rhetoric of the DOT's Gastronomy Tourism Roadmap 2024–2029, and until the diaspora network is activated as a structured soft-power engine rather than left to self-organize, Filipino cuisine risks remaining what it is today: world-class food that the world has not yet been given an easy opportunity to eat.
Key Points
The Chasm Between International Awards and Global Market Presence
Filipino cuisine has accumulated remarkable critical recognition in a short span: TasteAtlas ranked sinigang the world's best-rated vegetable soup in 2021 with a score of 4.8 out of 161 contenders, then placed chicken inasal third in the world among chicken dishes (rating 4.4) on its 2026 "50 Best Chicken Dishes" list, with chicken adobo appearing at 40th on the same ranking (rating 4.1). The inaugural Michelin Guide Philippines in 2025 awarded one two-star restaurant — Helm, led by Chef Josh Boutwood — and eight one-star restaurants, giving Filipino fine dining its first formal global certification from the world's most recognized culinary authority. Yet the global Filipino restaurant market, estimated at roughly $3.8 billion in 2024, concentrates more than 54 percent of its revenue in the Asia-Pacific region, meaning less than half of the market operates outside the Philippines itself. Globally, Thai restaurants number 17,478, Japanese restaurants reach approximately 200,000, and South Korean restaurant brands operate 4,644 locations across 56 countries — while Filipino restaurants, despite a 5.41-million-strong diaspora in the Americas alone, fall dramatically short of those numbers in virtually every major non-diaspora market. This is the central paradox of Filipino food in 2026: a cuisine whose quality is internationally certified but whose market presence remains largely invisible outside Filipino communities. The gap between the trophy case and the restaurant map is not narrowing on its own and requires deliberate strategy to close.
Five Centuries of Colonial History and the Single-Icon Problem
The Philippines' 500-plus years of colonial rule under Spain, the United States, and Japan produced the most hybridized culinary tradition in Asia, and that complexity is the root cause of the single-icon problem. Adobo takes its name from Spanish but its technique from pre-colonial preservation methods; pancit traces to Chinese noodle culture; lechon is a Spanish whole-roast adapted to local context; and caldereta began as a Spanish stew before becoming something distinctly Filipino. This layered identity contrasts sharply with Thailand, which was never colonized and could build a singular pad thai narrative around genuine cultural continuity, and Japan, whose millennia of culinary evolution produced sushi and ramen as unmistakable icons. For global marketing purposes, the inability to name a single dish and say "that is Filipino food" creates a real competitive disadvantage — international food media rewards a strong, memorable identity, and Filipino cuisine's distributed richness doesn't compress into a single frame easily. However, the same complexity that complicates the marketing pitch is also what makes Filipino food genuinely interesting: its flavor vocabulary can speak to Spanish, Chinese, American, and indigenous palates simultaneously, which is a form of universal accessibility that single-icon cuisines cannot replicate. The challenge is finding the narrative frame that converts this hybridity from a liability into a brand identity — and that is a marketing problem, not a culinary one, which means it is solvable with the right strategy and resources.
The Michelin Guide Philippines — Prestige Without a Trickle-Down Pipeline
The October 30, 2025 Michelin Guide Philippines debut awarded Chef Josh Boutwood's Helm a two-star rating, with eight additional restaurants earning one star each — including Gallery by Chele, Toyo Eatery, and Hapag — while no restaurant received three stars. Michelin International Director Gwendal Poullennec's characterization of Filipino cuisine as "bold, generous, and deeply personal" gave the industry a usable promotional line, and Michelin's self-directed entry without government sponsorship — unlike its entries into Thailand and Singapore — signals that Manila's fine-dining ecosystem has genuine commercial pull independent of official promotion. The concern, however, is structural: every starred restaurant operates in the contemporary Filipino fine-dining register, meaning the Michelin recognition creates a high-end image of Filipino cuisine without providing a pathway for the everyday cooking traditions — turo-turo, carinderia, street-side inasal grills — to reach official international recognition. The Bib Gourmand category, which has historically spotlighted quality affordable cooking in other markets, has not yet been applied to the Philippines, leaving no formal recognition route for the democratic food culture that represents most Filipinos' actual daily eating. The Tokyo ramen precedent — where Michelin stars for ramen shops elevated the entire global perception of ramen — worked because tens of thousands of ramen restaurants were already installed worldwide to amplify the prestige; Filipino cuisine's Michelin moment arrives before that distribution infrastructure exists, which means prestige could calcify into a fine-dining stereotype before it broadens into mainstream awareness.
Government Strategy Without Budget — The DOT Roadmap's Credibility Problem
The Department of Tourism's Gastronomy Tourism Roadmap 2024–2029 sets ambitious targets — Southeast Asia's premier gastronomy tourism destination by 2029 — and includes specific structural plans: farm-to-table restaurant development, indigenous food trails, designated gastronomy zones in Manila, Pampanga, Cebu, and Iloilo, and a local ingredient certification system comparable to Europe's protected designation of origin frameworks. The geographic targeting is strategically sound: Pampanga's national reputation as the Philippines' culinary capital and Iloilo's identity as the birthplace of chicken inasal make them natural pilot zones with established domestic brand equity. The roadmap's critical deficiency, verified by Business Mirror, is the absence of any publicly disclosed investment figure — a strategy without a stated budget carries no external accountability. Thailand's Global Thai program attached 500 million baht (roughly $15 million) in startup capital to recipe standardization, chef-deployment programs, and restaurant certification infrastructure, producing a 3.2x expansion in overseas restaurant numbers over two decades. South Korea's agriculture ministry and aT directly supported 139 restaurant brands in establishing 4,644 overseas locations, creating a structural support system rather than leaving expansion to individual initiative. A roadmap without disclosed funding signals to diaspora entrepreneurs, international investors, and culinary tourism operators that the Philippines' gastronomy push may not have the institutional staying power that sustained Thailand's and Korea's programs — and that impression, once formed, is difficult to reverse.
The 10.8 Million Overseas Filipinos — Southeast Asia's Most Underactivated Culinary Asset
DFA statistics for 2024 place the total overseas Filipino population at over 10.8 million — 5.41 million in the Americas, 2.44 million in Asia-Pacific, and 2.1 million in the Middle East — a geographic distribution that dwarfs any comparable Southeast Asian diaspora in both scale and global coverage. PSA official data shows 2.19 million overseas Filipino workers departed for work in 2024 alone, sending home ₱262 billion (approximately $4.46 billion), demonstrating the depth of economic connectivity between overseas Filipinos and their home country. The 2026 Diaspora Summit's "Connected by Taste" theme and CFO Secretary-General Dante Ang II's characterization of 6 million non-resident Filipinos as "a core soft power asset" represent institutional recognition of what this network could do for Filipino cuisine globally — but declaration is not the same as program design. South Korea's model is instructive: rather than simply celebrating the existence of a Korean diaspora, the government created direct financial and logistical support for diaspora-connected restaurant brands to establish overseas locations, resulting in 4,644 locations across 56 countries. If the Philippines built a comparable program — startup financing, culinary brand playbooks, supply-chain connections for diaspora entrepreneurs in New York, Los Angeles, Dubai, and other diaspora-dense cities — the existing 10.8-million-person distribution network would transform from an informal ambassador corps into a structured market creation engine whose geographic reach no competitor can match.
Positive & Negative Analysis
Positive Aspects
- Repeated, Multi-Source International Quality Certification
Filipino cuisine has now been formally validated by multiple internationally recognized platforms in a remarkably short time frame, providing the kind of third-party credibility that no amount of self-promotion can manufacture. TasteAtlas ranked sinigang the world's best-rated vegetable soup in 2021 with a score of 4.8, named chicken inasal third globally in the chicken dish category with a 4.4 rating in 2026, and placed chicken adobo 40th on the same list — demonstrating consistent recognition across multiple dish categories. Michelin Guide Philippines debuted in 2025 with a two-star and eight one-star awards distributed across nine Manila restaurants, representing the international fine-dining establishment's formal endorsement of Filipino cuisine as globally competitive. The Philippines was then selected to host the 10th UN Tourism World Forum on Gastronomy Tourism, a 150-plus-country event representing institutional recognition from the global tourism governance community. Each of these endorsements arrives from an independently credible evaluative framework — TasteAtlas is crowd-validated, Michelin is expert-curated, and the UN forum is a government-and-industry consortium — meaning the quality signal is converging from three entirely different directions simultaneously. Crucially, Michelin's self-directed entry into the Philippines, rather than by government invitation as was the case with Thailand and Singapore, signals that Manila's fine-dining market has genuine commercial magnetism independent of official promotion — a stronger credibility signal than sponsored entries. For a cuisine that has historically lacked international marketing infrastructure, this convergence of third-party validation provides the most valuable asset at the start of a global culinary push: objective evidence that the food is worth seeking out.
- The 10.8 Million Diaspora — Geographically Distributed, Economically Connected, Culturally Motivated
No country in Southeast Asia has an overseas community matching the Philippines' diaspora in scale, geographic coverage, or cultural cohesion — and all three of those characteristics matter enormously for building a global food culture. The 10.8 million figure breaks down as 5.41 million in the Americas, 2.44 million in Asia-Pacific, and 2.1 million in the Middle East — a distribution that places Filipino communities in virtually every major global culinary market simultaneously. PSA data confirms that 2.19 million OFWs were deployed in 2024 alone, sending ₱262 billion (approximately $4.46 billion) home, demonstrating economic connectivity that could underpin formal diaspora restaurant support programs if properly channeled. Many members of this network are already informal food ambassadors — cooking and sharing Filipino food within their host communities, running pop-up events, and building micro-audiences for Filipino cuisine in cities where Filipino restaurants are rare or nonexistent. The 2026 Diaspora Summit's declaration that 6 million non-resident Filipinos constitute 'a core soft power asset' reflects a political recognition that could translate, with the right program design, into something structurally equivalent to what Korea's overseas community did for kimchi — creating demand through community cooking before formal restaurant expansion followed. In cities like New York, Los Angeles, and London, Filipino-origin food entrepreneurs have already demonstrated market viability at the pop-up and food truck level; systematic government support in the form of financing, brand guidelines, and supply-chain access would accelerate what diaspora entrepreneurs are already inclined to do on their own initiative.
- Tourism Revenue Growth and the Existing Food Economy Baseline
The Philippines' tourism sector entered 2025 with a demonstrated growth trajectory that gives the gastronomy tourism strategy a healthy foundation to build on, rather than needing to create market demand from scratch. The 2024 tourism revenue of ₱760 billion represented a record high, up 9.04 percent year-on-year and 26.75 percent above the 2019 pre-pandemic peak — a recovery curve that demonstrates the market's fundamental health and visitor demand resilience. Food and beverage expenditure accounted for 17.1 percent of that tourism revenue, or roughly ₱118.5 billion (about $2.1 billion) — a substantial food economy that exists before any deliberate gastronomy tourism strategy has been meaningfully implemented, suggesting enormous upside if that strategy is actually executed. South Korea's status as the largest source market at 26.46 percent of 2024 arrivals creates an interesting secondary opportunity: Korean visitors already enthusiastic about culinary tourism experience Filipino food firsthand and carry that exposure back to one of the world's most food-obsessed consumer cultures, creating organic reverse-direction word-of-mouth without any marketing spend required. The structural positioning of food as nearly a fifth of total tourism spending means that even incremental improvements in Filipino gastronomy's international visibility carry measurable financial implications — a one-percentage-point increase in food spending share on a ₱760 billion base represents roughly ₱7.6 billion in additional annual revenue. The baseline is strong enough that strategic investment in gastronomy tourism does not need to build demand from zero — it needs to deepen and extend demand that already demonstrably exists.
- Multi-Icon Cuisine Structure as a Long-Term Competitive Advantage
The very characteristic that complicates Filipino cuisine's marketing pitch in the short term — the absence of a single iconic dish — may be its greatest long-term structural advantage over single-icon cuisines like Thai or Japanese food. A cuisine built around multiple entry points is inherently more resilient: if adobo doesn't resonate with a particular consumer segment, inasal might; if sinigang is unfamiliar, lechon is accessible as a celebration dish familiar in concept if not in name; if grilled chicken speaks to one diner, a sour tamarind broth speaks to another. This multi-entry-point structure mirrors Italian cuisine's architecture, which never relied on a single dish to conquer global tables — it deployed pizza, pasta, risotto, espresso, and gelato simultaneously across different dining occasions and price points, becoming arguably the world's most universally loved food culture without ever forcing a "one dish to rule them all" decision. Mexican food achieved a similar result with tacos, burritos, guacamole, and ceviche as simultaneous ambassadors to different palates, and Korean food expanded through kimchi, Korean fried chicken, bibimbap, and tteokbokki reaching different consumer bases concurrently. Filipino cuisine's adobo addresses the comfort-food seeker; inasal addresses the grill enthusiast; sinigang addresses the soup devotee; lechon addresses the special-occasion celebrant — four completely different consumption contexts representing four different potential gateway experiences. The challenge is creating a brand umbrella strong enough that each of these encounters registers as "this is Filipino food" rather than leaving the diner uncertain about what culinary tradition they just experienced — and that is a narrative design challenge, not a product quality challenge.
Concerns
- A Gastronomy Roadmap Without a Disclosed Budget Is a Strategy Without Accountability
The most fundamental structural weakness in the Philippines' gastronomy strategy is the absence of publicly committed investment, which transforms an ambitious plan into a document without external accountability. The DOT's Gastronomy Tourism Roadmap 2024–2029 articulates clear strategic directions — farm-to-table development, food trails, gastronomy zones, ingredient certification — but Business Mirror's direct verification confirmed that no specific budget figure was disclosed alongside the plan. This is not a minor administrative gap: it is the difference between a government-backed program with measurable targets and a policy document that stakeholders, investors, and diaspora entrepreneurs cannot rely upon when making their own investment decisions. Thailand's Global Thai program demonstrated the model: 500 million baht (roughly $15 million) committed at launch, attached to recipe standardization, chef deployment abroad, and a restaurant certification system across 70 countries — producing a 3.2x expansion in overseas restaurant numbers over two decades and a Thai Select certification program covering approximately 1,400 restaurants in 70 countries. South Korea's agriculture ministry and aT formalized support for 139 restaurant brands in establishing 4,644 overseas locations, creating a structural support system rather than leaving expansion to individual initiative. A roadmap without disclosed funding signals — whether intentionally or not — that the government is not prepared to back its ambitions with financial commitment, which in turn tells diaspora entrepreneurs, international investors, and culinary tourism operators that the Philippines' gastronomy push may not have the institutional staying power that sustained Thailand's and Korea's programs over multiple political administrations.
- Michelin Recognition Risks Entrenching a Fine-Dining Narrative That Excludes Everyday Filipino Food Culture
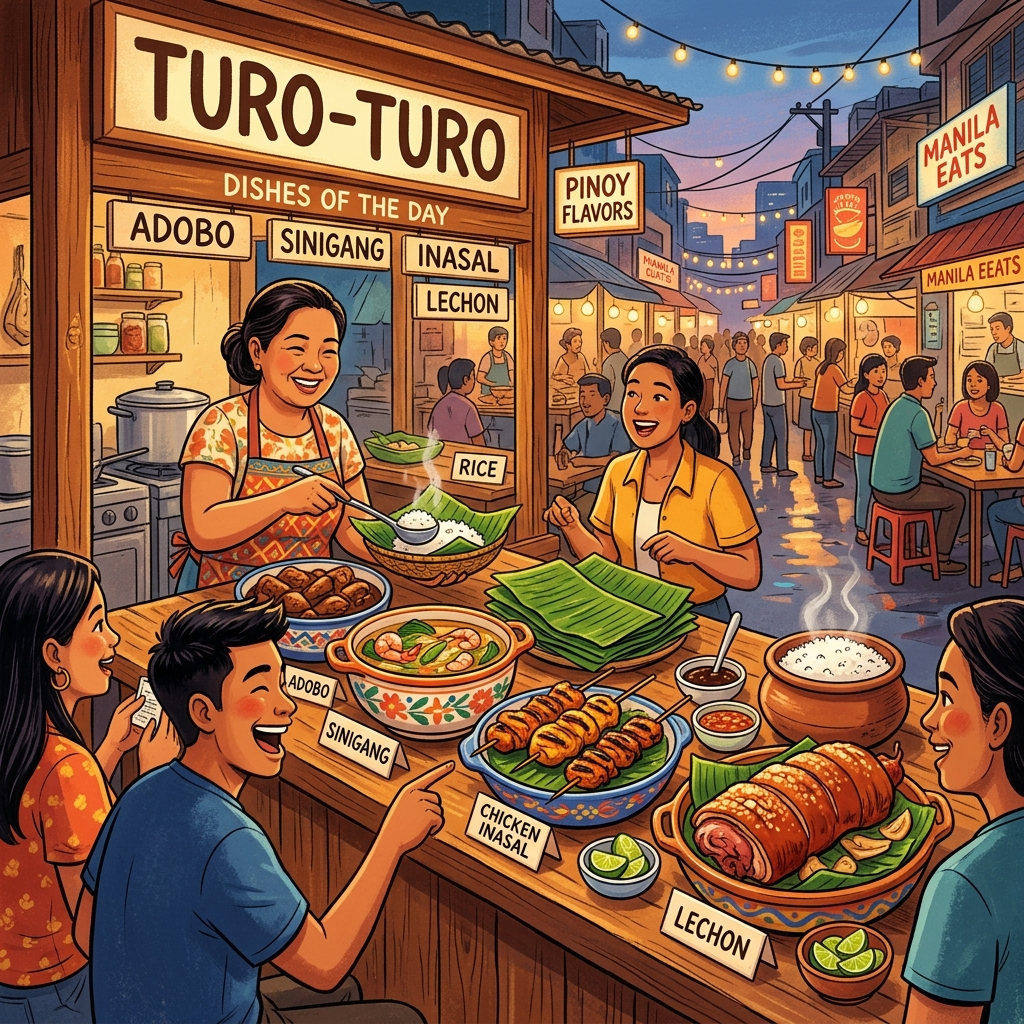
All nine Michelin-starred restaurants in the Philippines operate in the contemporary fine-dining register, raising a serious concern about what international image of Filipino cuisine the recognition is building. Turo-turo — the steam-table cafeteria where diners point at dishes through glass — and carinderia cooking represent the democratic, communal core of Filipino food culture, providing affordable, home-style meals to millions of Filipinos daily and constituting what most of the country's 7,641 islands' worth of culinary heritage actually tastes like in practice. Iloilo's street-side inasal grills, where charcoal-marinated chicken basted with annatto oil feeds laborers, students, and families, embodies a completely different dimension of Philippine culinary heritage than what Michelin-starred tasting menus currently represent to international audiences. The risk is not that fine-dining restaurants exist — they absolutely should — but that without a counterbalancing recognition pathway for everyday cooking, international food media will follow Michelin's narrative lead and construct a portrait of Filipino cuisine as fundamentally upscale and rarefied, which is both inaccurate and commercially limiting because it prices out the vast majority of potential customers worldwide. The Bib Gourmand category, which would provide a formal recognition pathway for quality affordable cooking, has not been applied to the Philippines, leaving turo-turo and carinderia with no route to official international recognition. Specialist food media like Sawsawan have noted that the gap between "Michelin-recognized Filipino food" and "food Filipinos actually eat" risks becoming permanent and self-reinforcing — a distortion with particularly high stakes given that the Michelin narrative is arriving before any significant overseas Filipino restaurant infrastructure is in place to counterbalance it.
- Stagnating Tourism Metrics Despite a Favorable PR Environment
The gap between Filipino cuisine's favorable international narrative and the actual tourism numbers coming out of 2025 is a meaningful warning signal that demands honest assessment rather than optimistic dismissal. Total arrivals of 6,484,060 represented growth of just 0.76 percent year-on-year, foreign visitor growth barely registered at 0.27 percent, and overall tourism revenue retreated to approximately ₱694 billion from the 2024 record of ₱760 billion — a decline that occurred during the same period that Michelin entered Manila and the UN Gastronomy Tourism Forum hosting was announced. This stagnation is not occurring in a vacuum: Bangkok continues growing its visitor numbers, Ho Chi Minh City and Hanoi are aggressively marketing gastronomy as a travel draw, and the Philippines appears to be falling behind on execution speed even as it accumulates prestige events and favorable press coverage. The structural problem is not the lack of compelling stories — it is the absence of a marketing conversion infrastructure that turns those stories into booked flights and hotel nights, specifically cuisine-forward itinerary packages, domestic operator training in gastronomy tourism product development, and digital marketing calibrated around "eat Filipino food" as a trip motivator. If the 2025 revenue decline extends into 2026, the narrative risk is real: the Philippines becomes associated in global tourism markets with interesting headlines and disappointing execution, which is a harder reputation to reverse than starting from obscurity, because it requires overcoming an already-formed negative impression rather than simply filling a gap in awareness.
- The Absence of a Cultural Content Engine to Pair With Food Strategy
South Korea's K-Food success is inseparable from K-drama and K-pop: the entertainment content created global curiosity, food benefited from that curiosity in the form of recipe searches, restaurant visits, and supermarket purchases driven by audiences who wanted to participate in a culture they had encountered through screens, and BTS members eating on camera generated more Korean food interest than any individual marketing campaign could have achieved. Filipino OPM (Original Pilipino Music) has a devoted domestic fanbase, and Filipino dramas have a presence on streaming platforms including Netflix, but neither has yet generated the kind of sustained global cultural footprint that creates the automatic food-culture association seen with Korean or Japanese entertainment content. This absence means Filipino cuisine cannot rely on the passive culinary curiosity that entertainment fandoms generate — it must build awareness through deliberate food-first marketing, which is harder and more expensive than riding a pre-existing cultural wave that someone else has already built and paid for. The 10.8-million diaspora network could partially compensate for the lack of a global entertainment platform — individual diaspora members creating content about Filipino food on social media, running pop-ups, operating food trucks — but self-organized content is inherently inconsistent and unscalable compared to a national cultural industry providing systematic content tailored to drive culinary interest. A coherent content strategy that packages Filipino food stories alongside existing entertainment and cultural outputs would amplify every structural advantage the cuisine already has; the current absence of such a strategy means those advantages are compounding more slowly than their underlying strength warrants, and the gap is widening relative to competitors who have their cultural engine already running at full speed.
Outlook
The next six months pivot almost entirely around one event: the UN Tourism World Forum on Gastronomy Tourism, which the Philippines is scheduled to host in 2026 as the 10th edition of the forum. With participation from more than 150 countries, this event represents the most concentrated international food-and-tourism audience the Philippines has ever accessed as a host — not as an attendee, but as the country setting the agenda. The venue and exact dates remain unannounced as of this writing, but the 2024 Asia-Pacific regional edition in Cebu drew over 500 delegates; the global forum will be substantially larger in both scale and media footprint. The way the Philippines uses this platform will set the tone for the next several years of its culinary diplomacy effort.
Tourism Secretary Christina Garcia Frasco's declaration that "the Philippines is the perfect place to bridge cultures through food" is the right rhetorical framing — but rhetoric must be matched with execution. If the forum's opening reception features an immersive turo-turo experience, if the official dinner showcases inasal and sinigang alongside Michelin-starred reinterpretations, if the press kits tell the 7,641-island story with the depth it deserves, then 150 countries' worth of travel journalists and tourism ministers will leave having internalized a Filipino food narrative. If the organizational logistics are underprepared and the cuisine presentation is generic, the inverse is equally possible: the Philippines earns a reputation for hosting ideas it cannot execute. This forum is not a conference — it is a national branding examination, and the preparation quality will determine whether it becomes a turning point or a missed opportunity.
In the shorter term, the critical question is whether the Michelin launch converts from a cultural event into an economic driver before the momentum dissipates. Since the inaugural Michelin Guide Philippines ceremony on October 30, 2025, Manila's fine-dining scene has drawn measurably more international food media coverage, and Helm's two-star rating alongside eight one-star restaurants has collectively signaled that Filipino haute cuisine is globally competitive. Gastronomy travelers who plan international trips around Michelin-starred experiences are, for the first time, including Manila on their itineraries. The food and beverage share of tourism revenue, at 17.1 percent (roughly ₱118.5 billion in 2024), is already significant and structurally placed to grow if the right marketing infrastructure surrounds it.
But the 2025 tourism data is a sobering counterpoint: total arrivals reached 6,484,060, up just 0.76 percent; foreign visitor growth barely touched 0.27 percent; and overall tourism revenue slipped to approximately ₱694 billion from the record ₱760 billion of 2024. Michelin prestige alone is not moving the needle fast enough. Bangkok's gastronomy scene continues growing, and Vietnam's Ho Chi Minh City and Hanoi are aggressively marketing themselves as Asia's next culinary destinations. The Philippine competitive position in Southeast Asian gastronomy tourism is not worsening on quality grounds — it is stagnating on execution grounds. The next six months represent the window in which Michelin Manila either solidifies into a recurring circuit on international culinary travel routes or fades into the category of "interesting one-time story" — and which direction it goes depends on decisions being made right now.
Over the medium term — roughly six months to two years — the defining variable becomes whether the DOT's Gastronomy Tourism Roadmap 2024–2029 generates any visible on-the-ground outputs. The roadmap's framework is well-conceived: farm-to-table restaurant development, indigenous food trails, designated gastronomy zones in Manila, Pampanga, Cebu, and Iloilo, and a local ingredient certification system analogous to Italy's DOP protected designation of origin program. Pampanga, widely called the culinary capital of the Philippines, would be a logical pilot zone — its domestic culinary reputation is established and could anchor international food travel packages quickly. Iloilo's identity as the birthplace of chicken inasal offers an equally compelling anchor: building a formal inasal trail around authentic preparation traditions — the lemongrass-garlic-ginger marinade, the annatto oil basting, the charcoal heat — could create a tourism product that doesn't exist anywhere else on earth.
The local ingredient certification system, if executed, would add the "origin guarantee" premium that Italy's Parmigiano Reggiano and balsamic vinegar certifications built their international pricing power on. But all of this requires what Business Mirror confirmed is currently absent from the roadmap: a publicly committed budget. Without a disclosed funding commitment and the accountability structure that comes with it, the roadmap carries the risk of joining the Philippines' long history of well-intentioned government documents that never become infrastructure. My read is that if there are no visible pilot zone launches by the end of 2027, the current wave of international momentum will have passed its peak and the structural gap versus Thailand and Korea will have widened further.
The medium-term window is also when diaspora strategy needs to shift from ambition to architecture. The Philippines has more than 10.8 million overseas nationals — a network that dwarfs any comparable Southeast Asian diaspora in scale and geographic distribution. The 2026 Diaspora Summit's "Connected by Taste" theme and CFO Secretary-General Dante Ang II's framing of 6 million non-resident Filipinos as "core soft power assets" signal institutional recognition of the food-culture connection. But concept needs program design to become real. South Korea's approach is instructive: the Ministry of Agriculture, Food and Rural Affairs and aT didn't just cheer on Korean diaspora members who opened restaurants — they built a direct support infrastructure that helped 139 restaurant brands establish 4,644 locations across 56 countries. A comparable Philippine initiative could identify Filipino entrepreneurs in diaspora-dense cities — New York, Los Angeles, San Francisco, Dubai, Riyadh — and provide startup financing, brand playbooks, and supply-chain connections.
The 5.41 million Filipinos in the Americas alone represent a ready-made demand base in markets where Filipino cuisine is currently invisible. With 2.19 million OFWs sending home ₱262 billion annually, the economic connectivity already exists — the missing piece is redirecting a portion of that energy toward building Philippine culinary infrastructure in host countries. If the diaspora is systematically activated within this two-year window, global Filipino restaurant numbers could begin growing measurably. If it remains a summit talking point, the 10.8-million-person opportunity will continue operating at a fraction of its potential — which is precisely the waste that makes this moment so frustrating to observe from the outside.
Looking further out — two to five years — the fundamental question is whether Filipino cuisine can develop a brand identity strong enough to compete at K-Food's level without first having K-pop or K-drama as a cultural delivery vehicle. South Korea built a $13.03 billion food export engine partly by running K-drama and K-pop as decade-long cultural investments alongside the food strategy, creating a flywheel where entertainment content drove food curiosity. Filipino OPM (Original Pilipino Music) and the growing Netflix Philippines content slate are real cultural assets, but neither has generated the kind of sustained global fanbase that organically creates appetite for Philippine cuisine the way BTS generates appetite for Korean food. The long-term outlook is not bleak, though — the 14.5 percent projected annual growth rate for gastronomy tourism globally, combined with the Philippines' extraordinary ingredient diversity and pre-installed diaspora network, gives the country the ingredients for a compelling five-year story.
What Filipino cuisine probably should not attempt is replicating the single-icon model: building the Filipino equivalent of pad thai and hammering it globally until saturation. Filipino food's actual superpower is its multiplicity. Adobo speaks to the comfort-food seeker. Inasal speaks to the grill culture enthusiast. Sinigang speaks to the broth devotee. Lechon speaks to the celebrant. This multi-pillar structure is closer to Italian cuisine's model than to Thailand's concentrated single-dish push, and Italy never needed a single dish to conquer global tables. The Philippines doesn't either — but it does need a unified brand umbrella strong enough that any one of these dishes registers immediately as Filipino rather than leaving diners uncertain about what tradition they just tasted.
When I think about where this could go, three trajectories seem plausible — and the differences between them are determined almost entirely by government decisions being made in the next 12 to 24 months. In the most favorable scenario, the UN Gastronomy Tourism Forum is executed with precision and generates sustained international media coverage, the government allocates visible budget to the roadmap by mid-2027, at least one pilot gastronomy zone opens to formal tourist programming, and a structured diaspora restaurant support program launches in at least two or three major global cities. In this scenario, the global Filipino restaurant count begins growing measurably within three years, food and beverage's share of tourism revenue ticks upward from its current 17.1 percent base, and Filipino cuisine transitions from "critically acclaimed but invisible" to "critically acclaimed and findable."
In a middle-of-the-road scenario, government investment remains limited but bottom-up momentum continues — individual chefs, diaspora entrepreneurs, and food media drive a slow, organic expansion of Filipino food's international footprint, the global market grows at the projected 7.4 percent annual rate but doesn't accelerate meaningfully above that baseline, and Filipino cuisine remains more visible than today while still trailing Thai and Korean cuisine by a wide margin. In the most pessimistic scenario, the roadmap budget never materializes, the Michelin effect cements a fine-dining image that obscures everyday Filipino food culture from international view, and the 2025 tourism stagnation extends into 2026 and 2027. The leading indicators to watch are specific: whether a pilot gastronomy zone shows operational proof-of-concept by end of 2027, whether a government-backed diaspora restaurant program is formally announced and funded, and whether tourism revenue returns to year-on-year growth in 2026.
What I want to emphasize as a closing thought is that Filipino cuisine's global underperformance — if it continues — will not be a culinary failure. Chicken inasal ranking third in the world in its category, sinigang winning the world's best vegetable soup in 2021, and Michelin entering Manila on its own commercial assessment all confirm that the food itself is not the problem. A tourism market where food and beverage expenditure already represents approximately ₱118.5 billion annually — within a global gastronomy tourism segment growing at 14.5 percent per year — is not a market lacking potential. The arithmetic of what strategic investment could unlock is genuinely significant: even modest acceleration above the baseline growth rate, compounded over five years alongside diaspora restaurant expansion, would transform the current picture substantially.
But the arithmetic only works if three things move simultaneously: real government budget behind the roadmap, systematic diaspora activation rather than aspirational summits, and a brand narrative that holds turo-turo and Michelin stars in the same frame without letting either eclipse the other. Thailand proved that 500 million baht and sustained institutional commitment can triple a country's overseas restaurant presence in two decades. South Korea proved that aligning cultural content with food exports can generate $13 billion in annual food trade. The Philippines has both the food and the global community already in place. The question for 2026 and beyond is whether the people responsible for deploying those assets will move from declaring ambition to committing budget. If they do, adobo's moment on the global table is overdue but entirely achievable. If they don't, the world will keep eating pad thai and wondering why they have never had sinigang.
Sources / References
- Michelin Launches In The Philippines With 2026 Stars: One Two-Star And Eight One-Star Restaurants. — Forbes
- 2 PH Chicken Dishes Among 50 Best in the World. — Manila Times
- Philippines to Host 2026 UN Tourism World Gastronomy Forum. — Philippine Tribune
- Results of the 2024 Survey on Overseas Filipino Workers. — Philippine Statistics Authority
- Korea Records Highest Food Export. — Business Korea
- DOT Rolls Out 5-Yr Plan to Boost Food, Gastronomy Tourism. — Business Mirror
- Number of Thai Restaurants Significantly Increases Globally. — Pattaya Mail.
- Korean Restaurant Chains Operating Over 4,600 Overseas Outlets: Data. — Korea Times